
Intelligence Brief
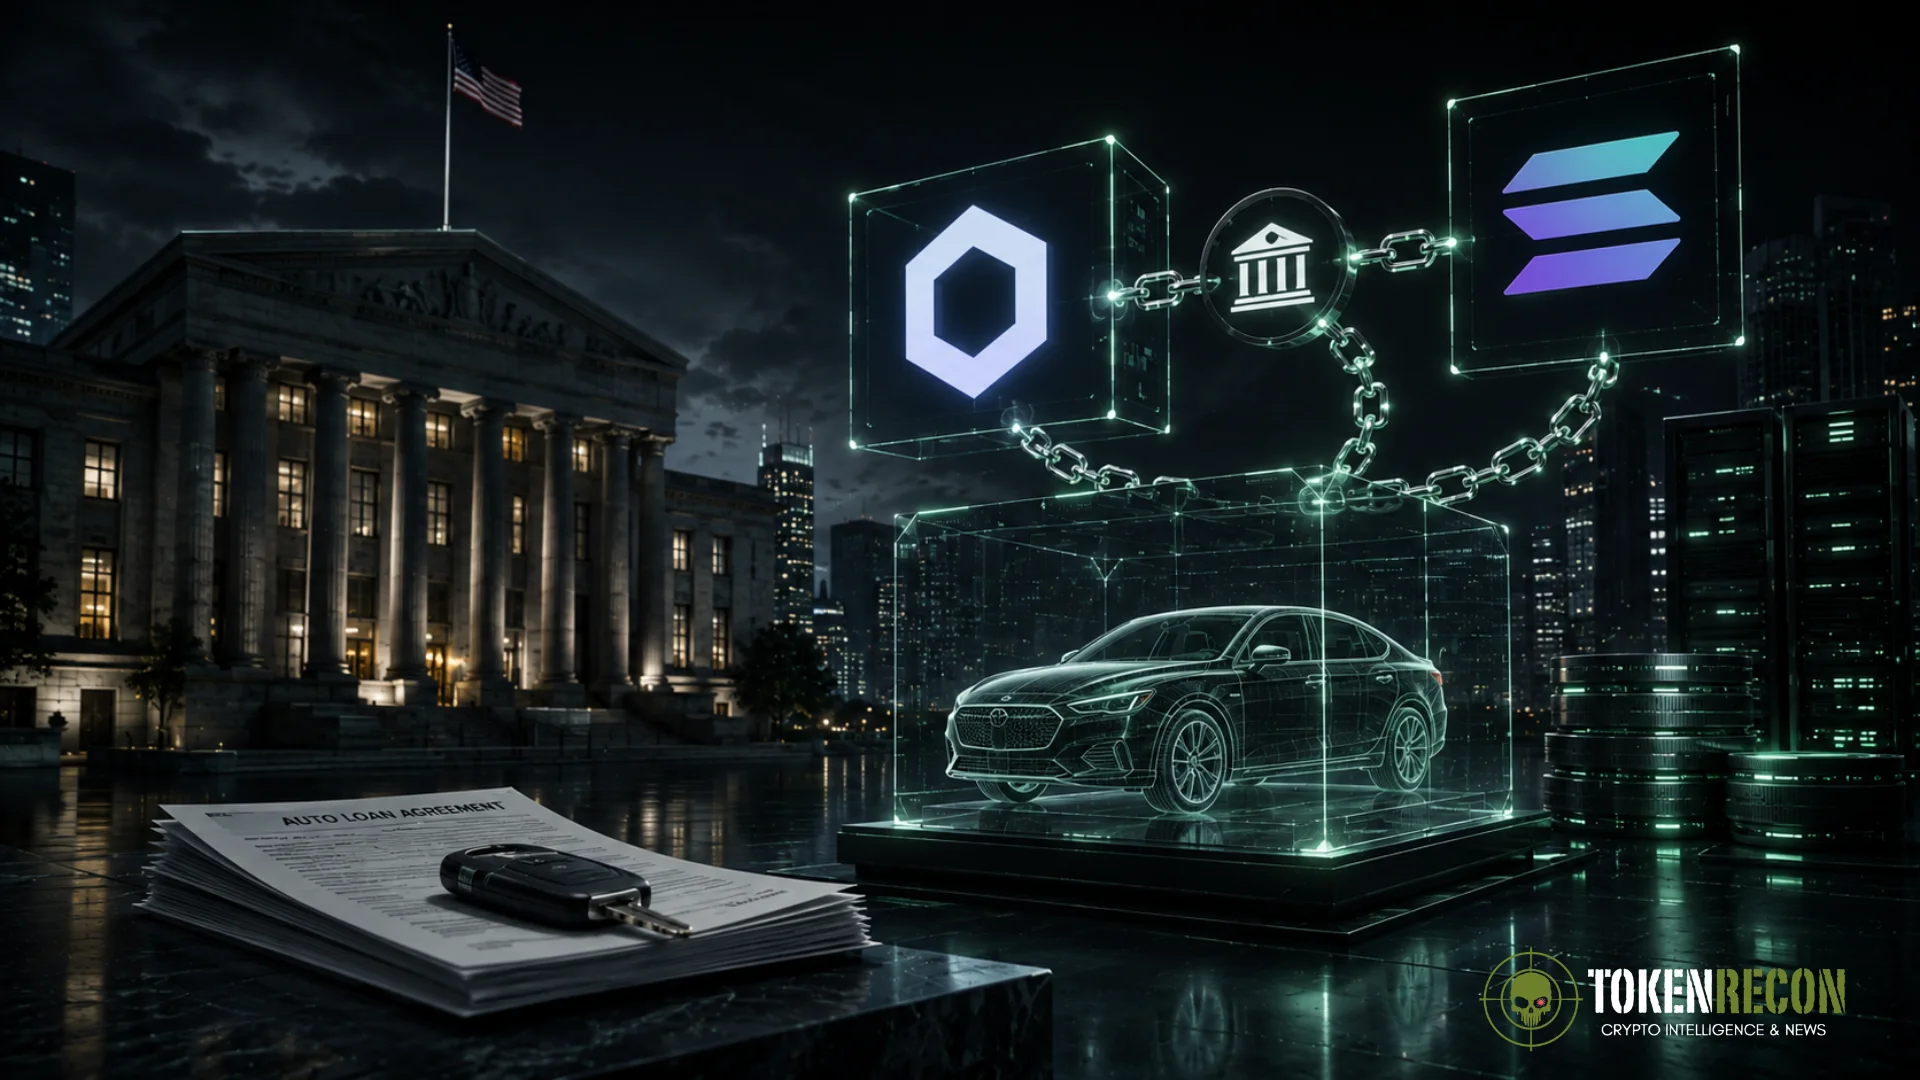
Chainlink infrastructure is powering a new tokenized credit product backed by U.S. auto loans, bringing exposure to part of the $1.6 trillion U.S. auto lending market onto public blockchain rails.
Hastra has launched its AUTO markets on Solana, using Chainlink Data Streams to deliver real-time loan data while sourcing underlying assets through Figure and Agora Data. The product is also integrated with Kamino, enabling lending and looping strategies for DeFi participants.
Chainlink Powers $1.6T US Auto Loan Market Onchain
Hastra’s (@HastraFi) AUTO markets are now live on Solana (@solana), backed by U.S. auto loans originated by Figure (@Figure).
The product uses Chainlink (@chainlink) Data Streams to bring real time loan data onchain. Loans are… pic.twitter.com/R8JWnVehrk
— BSCN (@BSCNews) July 30, 2026
Why It Matters
Tokenization continues expanding beyond Treasury bills and private credit into consumer finance.
Auto loans represent one of the largest traditional credit markets in the United States. Bringing verified loan performance onchain creates another bridge between conventional financial assets and decentralized liquidity, expanding the range of real-world collateral available to DeFi.
Key Developments
Hastra launched AUTO markets on Solana, backed by U.S. auto loans originated through Figure.
Chainlink Data Streams provide real-time loan data, while Agora Data supplies the underlying loan information through Figure Forge.
Kamino has added support for AUTO, allowing users to deploy lending and leverage strategies around the tokenized asset.
Hastra described the launch as an early step toward building cross-chain yield products backed by real-world financial assets.
Intelligence Assessment
This launch reflects the next phase of real-world asset adoption.
Rather than tokenizing assets alone, projects are now combining tokenization with live data infrastructure, automated settlement and DeFi liquidity. Chainlink’s role extends beyond price feeds by supplying continuous data that institutions require before placing regulated financial products on public blockchains.
If similar models expand into mortgages, consumer credit and commercial lending, blockchain networks could capture a larger share of traditional financial activity without replacing existing lenders.
Risk Assessment
Tokenized credit products remain dependent on the quality of the underlying loans.
Performance will ultimately depend on borrower repayment rates, servicing standards and reliable data delivery. Regulatory treatment of tokenized consumer credit also remains an evolving area that could influence institutional participation.
Bottom Line
Chainlink’s latest integration moves another segment of traditional finance onto blockchain infrastructure. By connecting $1.6 trillion in U.S. auto lending to DeFi through verified data and tokenized credit, the industry continues shifting from tokenizing assets to building complete financial markets around them.