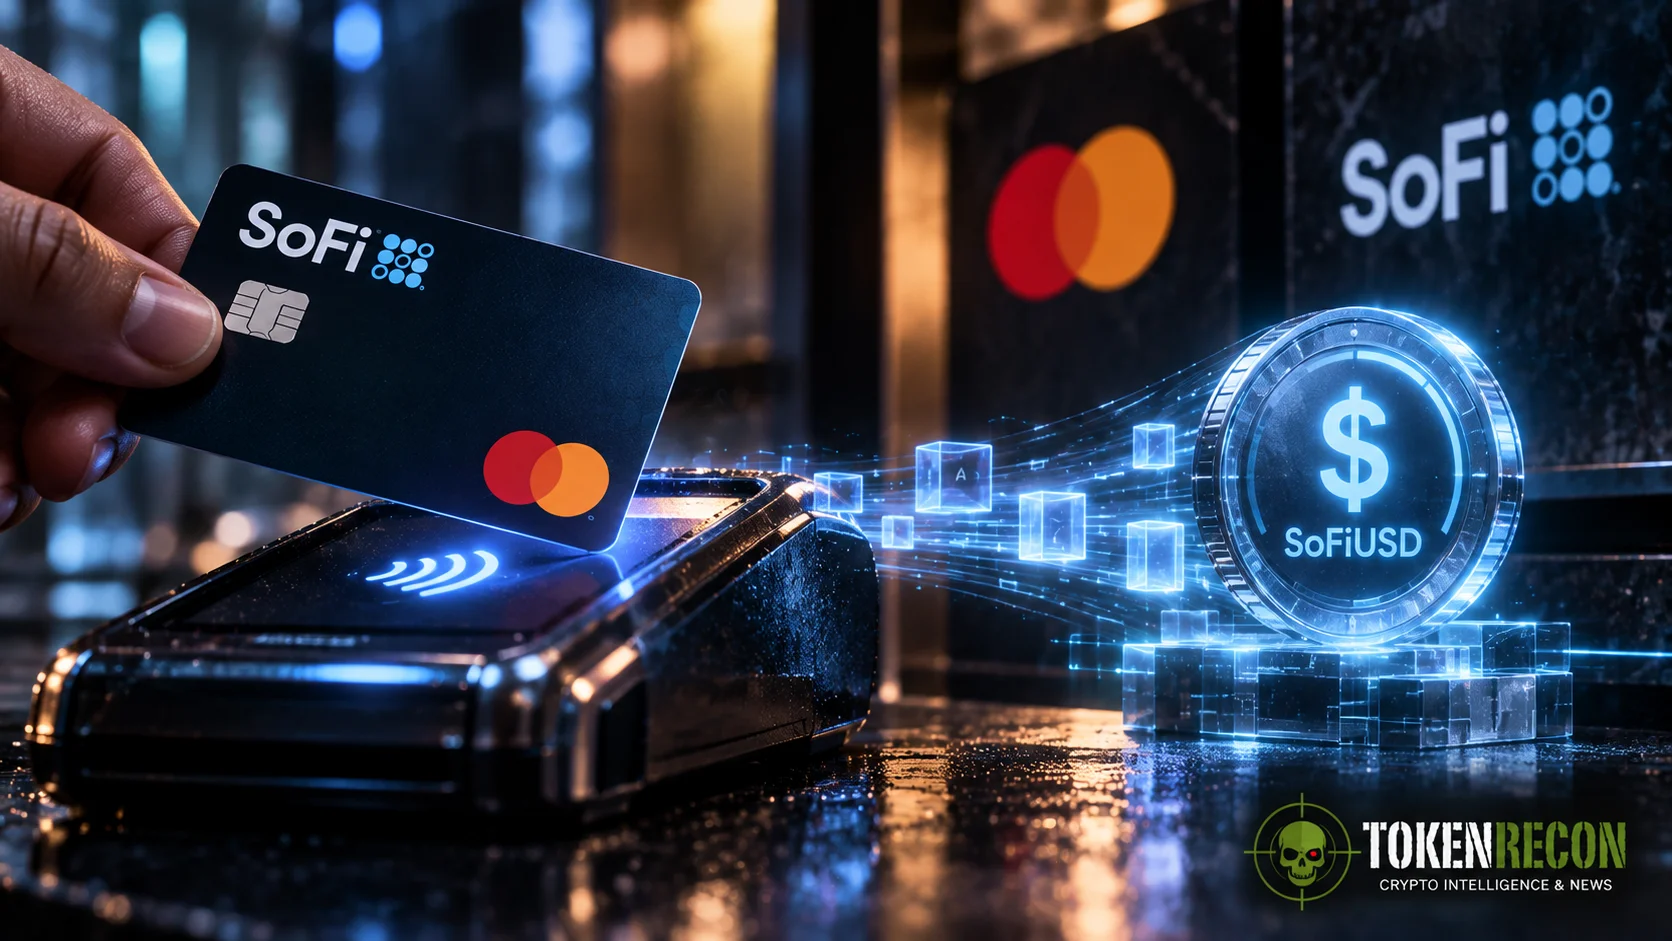
SoFi and Mastercard announced that stablecoin settlement is now live across SoFi Bank’s debit and credit card program, with SoFi migrating a program expected to process more than $25 billion in annualized volume onto blockchain-based settlement using SoFiUSD. SoFi official announcement
This is not a proof of concept or a planned pilot.
Transactions are live.
SoFi says it is the first national bank to go live with stablecoin settlement across Mastercard’s global payments network.
The underlying stablecoin, SoFiUSD, is issued by SoFi Bank, an OCC-regulated nationally chartered bank. It is redeemable one-to-one for U.S. dollars and supported primarily by cash reserves.
The Card User Does Not Need to Know
The architecture is significant because it does not require consumers or merchants to become crypto users.
A customer can use an ordinary SoFi debit or credit card.
The merchant does not need to accept SoFiUSD.
The blockchain operates at the settlement layer behind the existing payment experience.
That distinction separates the development from many previous crypto-payment initiatives that required users to hold tokens, connect wallets or change checkout behavior.
Stablecoins are entering the financial plumbing rather than asking consumers to adopt a new payment interface.
From March Announcement to Production in Six Months
SoFi and Mastercard first announced the partnership on March 3.
At the time, they said SoFiUSD would become a settlement option across Mastercard’s network and that SoFi’s Galileo technology platform could eventually make the capability available to additional card issuers. Mastercard, March SoFiUSD settlement partnership announcement
Six months later, the first production deployment is operational.
SoFi is now moving its entire card program to the new settlement architecture rather than maintaining the blockchain component as a limited experiment.
The speed from announcement to production is worth noting. Traditional financial institutions have spent years experimenting with distributed ledgers without moving meaningful transaction volume onto them.
This deployment has a stated annualized transaction base above $25 billion.
SoFiUSD Enters the Stablecoin Competition
The project also introduces another form of competition into the dollar stablecoin market.
USDT and USDC dominate crypto-native dollar liquidity.
SoFiUSD represents a different model: a stablecoin issued directly by a federally regulated national bank and integrated into a major card network.
Mastercard is not choosing a single stablecoin architecture.
Its broader settlement program supports regulated stablecoins including USDC, PYUSD, USDG, USDP, RLUSD and SoFiUSD across networks including Ethereum, Solana, Arbitrum, Base, Polygon, Canton, Tempo and the XRP Ledger. Mastercard stablecoin settlement expansion
That structure suggests stablecoin settlement could become multi-issuer and multi-chain rather than consolidating around one token.
Merchants Could Be Next
SoFi says it is already discussing stablecoin settlement arrangements with large U.S. merchants, including multinational retailers and technology-service platforms, although the companies were not identified.
Merchant settlement could become more consequential than the card-program migration itself.
Conventional card settlement operates around banking schedules and intermediary infrastructure.
Blockchain settlement can potentially operate continuously.
SoFi says merchants using its banking infrastructure can receive settlement funds and withdraw them as cash around the clock.
The economic question is whether those operational improvements translate into lower costs, better liquidity management or faster access to funds.
Banks Can Follow Through Galileo
The next expansion route is Galileo.
SoFi’s technology platform provides infrastructure to financial institutions and fintech companies. The March Mastercard announcement said Galileo customers and their issuing banks would eventually be offered SoFiUSD settlement.
If that occurs, the technology can expand without every bank building its own blockchain infrastructure.
A bank could maintain the familiar card-network relationship while changing the settlement asset underneath it.
That is a very different adoption path from asking banks to become crypto companies.
Stablecoins Are Becoming Infrastructure
The broader pattern is increasingly clear.
Circle launched Arc.
The ECB launched Pontes for tokenized securities settlement.
The SEC opened a regulatory path for tokenized U.S. stocks.
Circle introduced Bitcoin-backed USDC borrowing.
Now SoFi and Mastercard have moved a large existing card program onto stablecoin settlement.
These developments are occurring across different parts of the financial system, but they point toward the same architectural shift.
Blockchain is increasingly being deployed behind conventional financial products.
TOKEN RECON ASSESSMENT
The $25 billion figure is what moves this development above the usual stablecoin partnership announcement.
SoFi and Mastercard are attaching blockchain settlement to existing payment volume rather than waiting for users to migrate into a new crypto ecosystem.
The decisive metric is now execution.
Token Recon will be watching actual SoFiUSD settlement volume, transaction costs, merchant adoption, Galileo bank integrations and whether Mastercard expands production settlement across additional stablecoins and blockchains.
If other banks follow, stablecoins may become less visible to consumers even as they become more important to the financial system.
That would mark a significant transition.
Crypto would no longer need users to consciously choose blockchain for blockchain infrastructure to handle their transactions.
Sources
SoFi, stablecoin settlement goes live across Mastercard network
Mastercard, SoFi and Mastercard partnership announcement
Mastercard expands settlement capabilities to regulated stablecoins
The Block, SoFi begins stablecoin settlement on Mastercard network